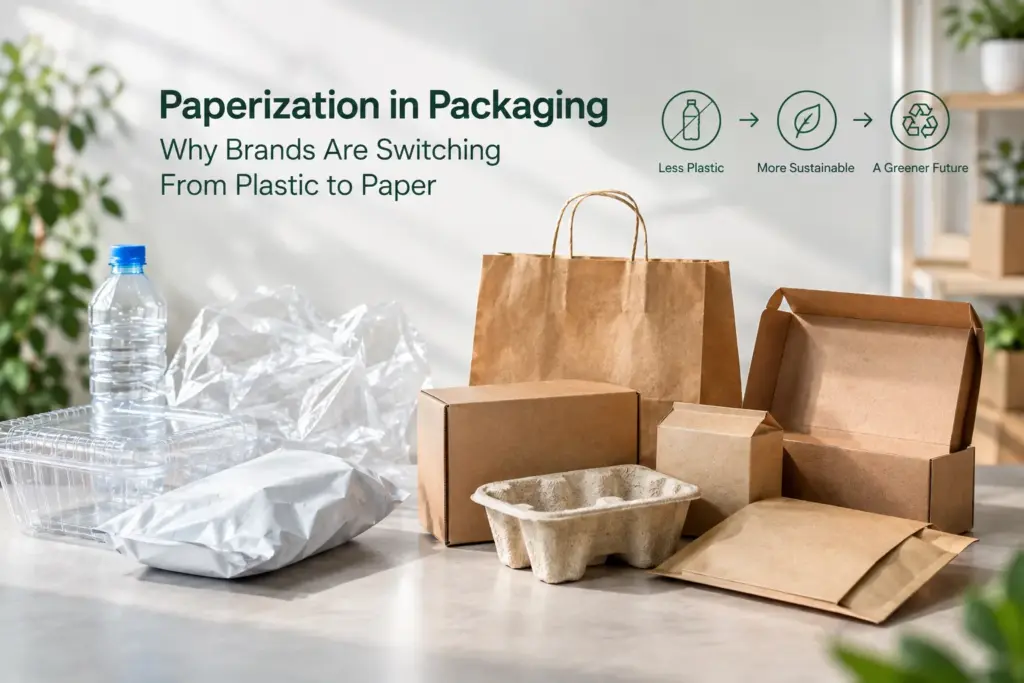
Across grocery aisles, e-commerce mailers, and cosmetic counters, a quiet material shift is underway. Fiber-based structures are showing up in places plastic used to dominate — from padded mailers to condiment sachets to cushioning inside electronics boxes. Industry publications have started calling this shift paperization packaging: the ongoing replacement of plastic and fossil-fuel-based materials with paper-based alternatives. This article explains what paperization actually means, why consumer expectations and new regulations are accelerating it, which paper formats are replacing plastic today, and how a brand should evaluate whether — and how — to make the switch.
What Is “Paperization” in Packaging?
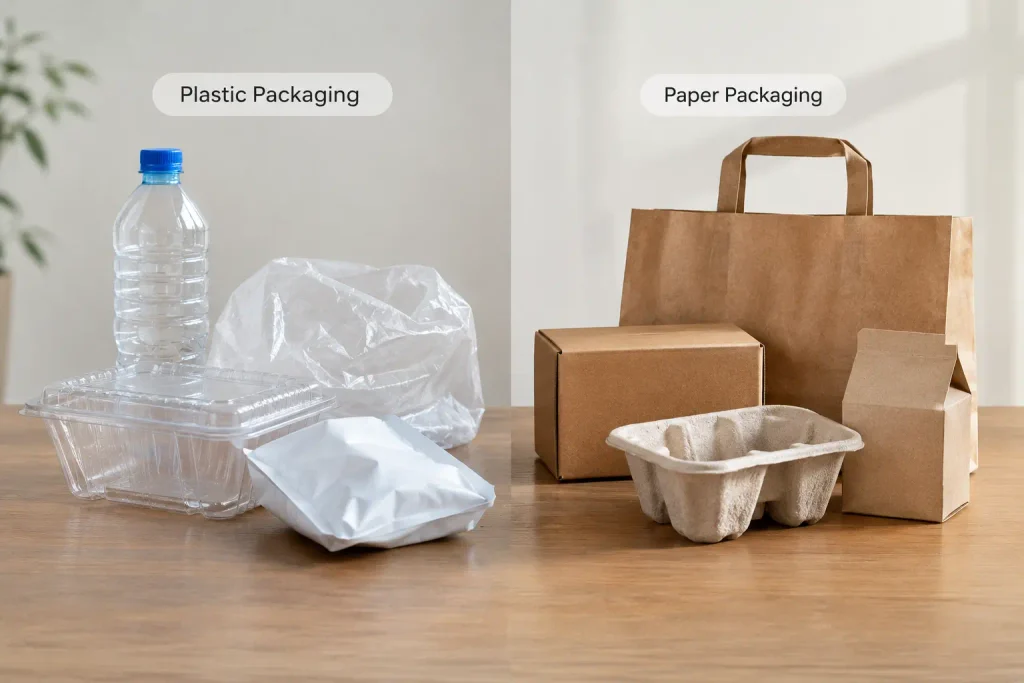
The term “paperization” comes from packaging trade media, not from a single regulatory body. Packaging Europe (2025) describes paperization as the growing use of paper for packaging jobs that plastics and other materials used to handle, noting that the trend has picked up meaningful momentum industry-wide. Packaging Digest (2024) frames it similarly: an increase in paper-based materials being used in place of plastic or other fossil-fuel-derived packaging, citing examples from companies such as Google, Amazon, Aldi, and Diageo as evidence of the shift reaching major retailers and CPG brands. More recently, Packaging Insights (2026) reported that the paperization trend continues to build, driven by brands looking to replace multi-layer plastic composites with fiber-based structures, alongside rapid development in functional barrier papers and converting technology.
In short: paperization in packaging is not a single material or certification — it’s a directional trend, and it applies unevenly depending on product category, barrier requirements, and local recycling infrastructure.
Pourquoi les marques passent du plastique au papier
Consumer Demand for Sustainability
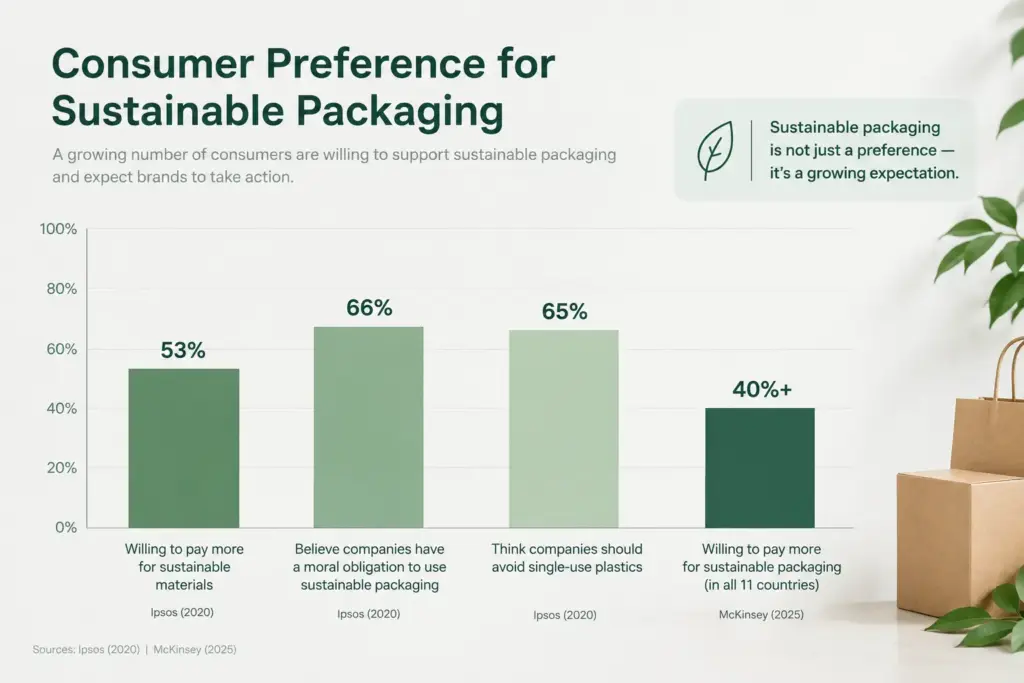
Consumer research over the past several years shows a consistent — though not universal — willingness to support sustainable packaging. Ipsos (2019) trouvé que 53% of consumers were willing to pay more for sustainable packaging (10% “significantly more,” 43% “a little more”), alors que 43% said they were not willing to pay extra. The same study found 66% of respondents believed companies have a moral obligation to use sustainable packaging, et 65% said companies should avoid single-use plastics.
More recent data confirms the trend hasn’t reversed. McKinsey’s 2025 Global Packaging Survey, covering more than 11,000 consumers across 11 pays, found that in every market surveyed, at least 40% of consumers were willing to pay more for sustainable packaging — with that figure exceeding 80% sur certains marchés. Even in Japan, typically a more price-sensitive market, willingness to pay held at 40%.
Pour les marques, this means plastic to paper packaging decisions are no longer purely a cost calculation — they intersect directly with purchase intent and brand trust.
Regulatory Pressure
Consumer sentiment is only part of the picture. Regulation is now a direct driver of paperization, particularly in the EU.
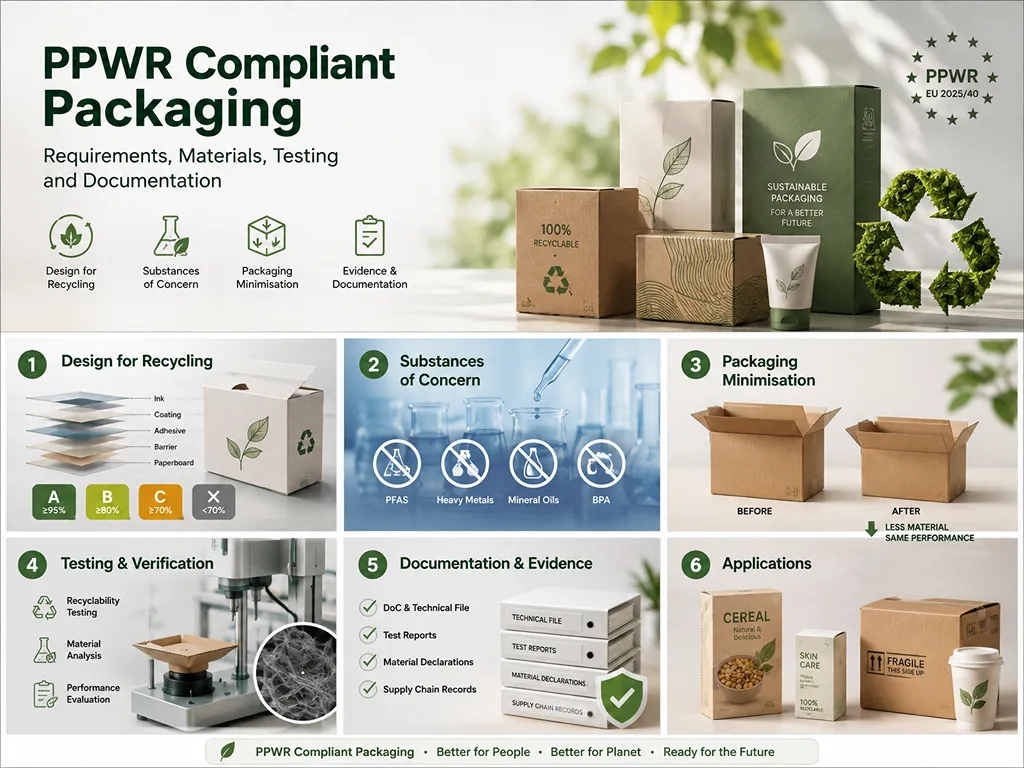
- Règlement de l’UE sur les emballages et les déchets d’emballages (PPWR) takes effect August 12, 2026, per the Commission européenne. It requires all packaging placed on the EU market to be recyclable by 2030, pushes brands to reduce unnecessary packaging and void space, and sets targets for reuse and refill systems.
- EU single-use plastic restrictions, per EUR-Lex, will prohibit specific single-use plastic packaging formats from January 1, 2030 — including plastic film for grouped goods, pre-packed fresh fruit and vegetable wrap, condiment sachets, hotel toiletry packaging, and ultra-light plastic bags.
- A critical nuance brands often miss: paperization is not simply “wrap it in paper and call it compliant.” Under EU guidance, composite packaging that is paper-based but contains 5% or more plastic content can still fall under the same restrictions as plastic packaging. Material composition, revêtements, adhesives, and end-of-life recyclability all matter — not just the outer visible layer.
- Beyond the EU, OECD (2024) reports that Extended Producer Responsibility (REP) frameworks — which hold producers accountable for a product’s full lifecycle, including post-consumer waste — are increasingly applied to packaging. UNEP (2024) notes that at least 40 countries now operate active EPR schemes, alongside growing support for single-use plastic bans globally.
Brand Image & Premium Positioning
Beyond compliance, paper packaging carries a perception advantage — particularly in premium and gift-driven categories like beauty, produits de beauté, and specialty food, where the unboxing experience is part of the product. Texture, print finish, and structural design on paper substrates can communicate craftsmanship in ways that standard plastic packaging often can’t. For a closer look at how this plays out specifically in beauty and personal care, voir sustainable cosmetic packaging.
Paper vs Plastic Packaging — Key Differences
Neither material is universally superior — the right choice depends on the product’s barrier needs, shelf life, shipping conditions, and target market’s recycling infrastructure. Here’s how the two compare across factors that matter most to B2B buyers evaluating paper alternatives to plastic:
| Factor | Plastic Packaging | Emballage en papier |
|---|---|---|
| Recyclabilité | Depends heavily on resin type and local sorting capability; multi-layer plastics are often not recyclable | Generally recyclable where uncoated or lightly coated, but composites with plastic content (≥5%) may not be |
| Recycling infrastructure | Fragmented globally; many regions lack facilities for flexible plastics | More broadly established fiber-recycling infrastructure in most markets |
| Imprimer & branding capability | Functional but limited texture options | Strong: gaufrage, estampage à chaud, revêtements doux au toucher, and structural die-cuts are widely available |
| Small-batch cost | Often lower per-unit cost at small volumes due to established molding processes | Cost varies by board weight, revêtement, et finition; can be competitive at mid-to-large volumes |
The takeaway for brands evaluating a plastic to paper packaging transition: check the full material spec, not just the visible substrate, before assuming a paper format is automatically the more sustainable or compliant choice.
Common Paper-Based Packaging Alternatives to Plastic
Several paper-based formats are directly displacing plastic equivalents across categories:
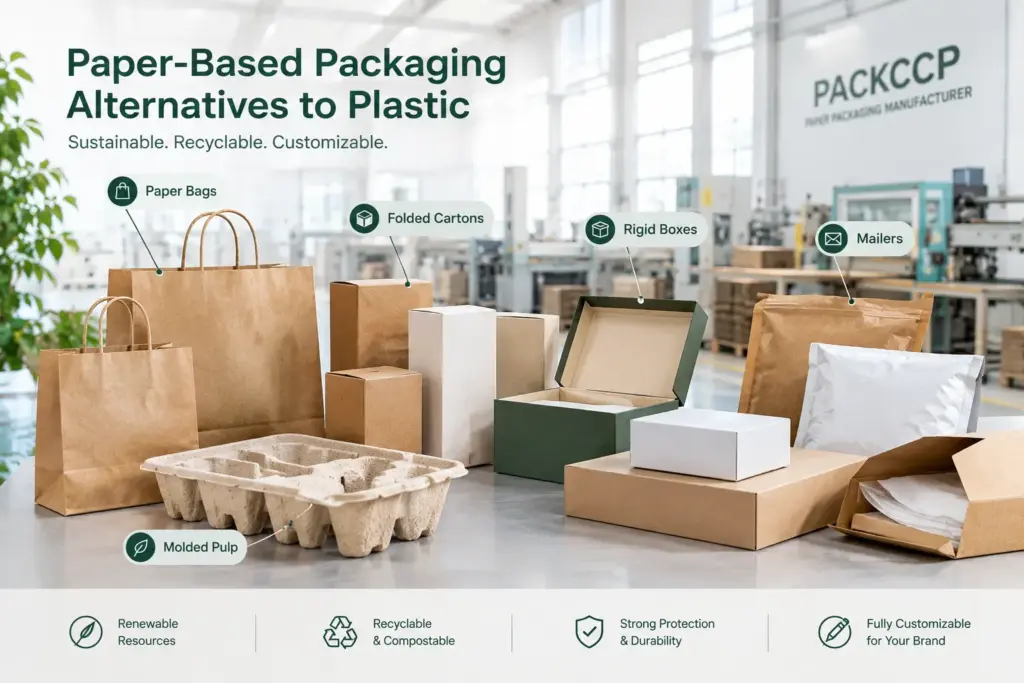
- Kraft paper bags — replacing plastic retail and grocery bags, now widely used in fashion, restauration, and gift retail. For a deeper look at sourcing options, voir fabricants de sacs en papier.
- Corrugated mailer boxes — increasingly replacing poly mailers in e-commerce shipping, offering better print branding and easier curbside recyclability.
- Rigid paper boxes — used where plastic clamshells or blister packs were once standard, particularly for electronics accessories and premium retail items. See folding carton solutions for structural options.
- Molded pulp and paper-based cushioning — replacing expanded polystyrene (EPS) and foam inserts for protective packaging, especially in electronics and fragile goods.
How to Choose the Right Paper Packaging for Your Brand
The right paper packaging spec depends heavily on the product category:
- Produits de beauté & soins de la peau: Prioritize print finish and structural rigidity for shelf presence; consider coated boards where moisture resistance is needed for liquid products.
- Nourriture: Barrier coatings are critical for grease, humidité, or oxygen sensitivity — not all paper substrates are food-safe without additional treatment.
- Électronique: Molded pulp or corrugated inserts need to match the product’s weight and fragility profile to prevent shipping damage.
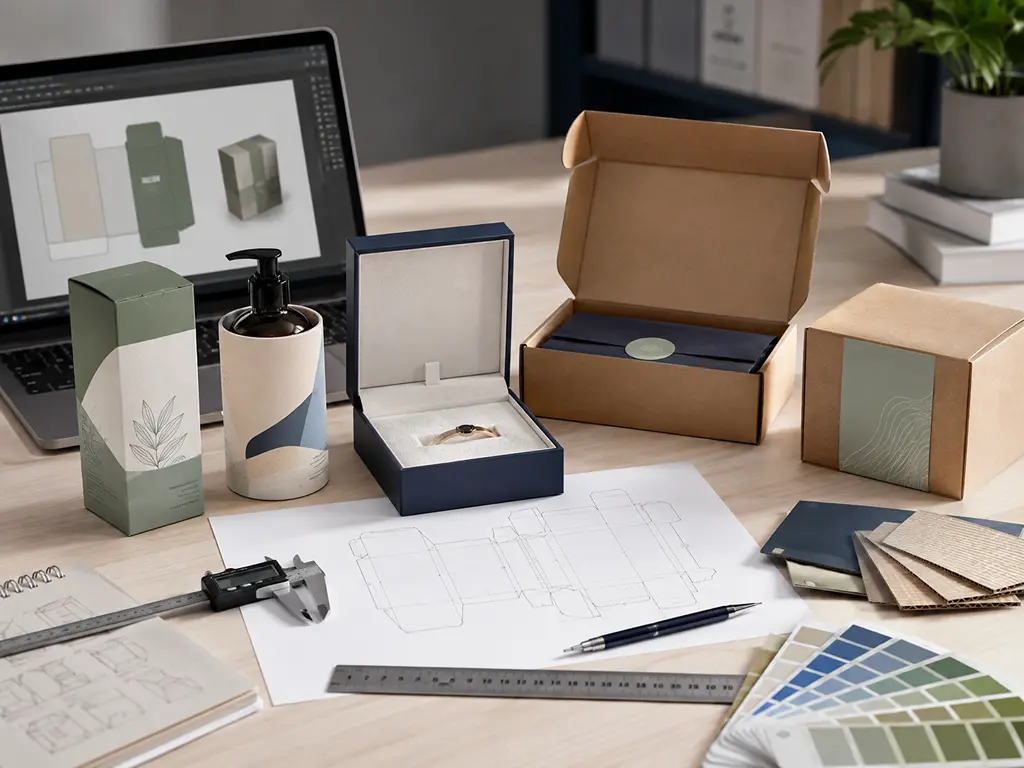
- Bijoux: Rigid box structures with strong print detail (foil, gaufrage) support the perceived value of the product.
Across all categories, three technical factors determine whether a paper format will actually work: paper/board thickness (matched to product weight and structural needs), coating type (for moisture, grease, or barrier requirements), et FSC certification (for brands making sustainability claims that need third-party verification). For more detail on matching paper type to design goals, voir choosing the right packaging paper.
Once you’ve identified the right specifications, the fastest way to validate cost and feasibility is to get an instant quote directly from a manufacturer who can confirm material availability and production timelines.
The Business Case — ROI of Switching to Paper Packaging
Paperization isn’t just a sustainability story — it’s a market-scale shift. According to Fortune Business Insights (updated August 31, 2026), the global custom packaging market was valued at USD 48.17 billion in 2025 and is projected to reach USD 50.63 billion in 2026, growing to USD 81.04 milliards par 2034 at a CAGR of 6.06% (2026–2034). Within that market, paper and paperboard account for 45.29% of share in 2026, and boxes specifically account for 37.57% — making paper-based formats the largest single material and format category in custom packaging today.
Real-world brand examples illustrate the environmental upside of moving toward paper and refill-based systems. Kiehl’s Mission Renewal program reports that its refill pouch formats use 61–94% less plastic compared to standard jars and bottles for the same products, and the brand reduced plastic volume by 414 tonnes across 2025 production through refill formats. Kiehl’s has also adopted FSC-certified, 100% recycled paper packaging sourced from Hansol Paper for select product lines. It’s worth noting this reflects targeted format and material shifts — not a complete conversion of all Kiehl’s packaging from plastic to paper.
For brands weighing whether premium paper packaging pays off commercially, it’s worth reading how packaging design choices tie directly to custom gift box brand loyalty.
Questions fréquemment posées
Paperization refers to the growing use of paper-based materials in packaging applications that were previously handled by plastic or other fossil-fuel-based materials, as tracked by trade publications like Packaging Europe and Packaging Digest.
It depends on volume and specification. Plastic often has a cost edge at very small batch sizes due to established molding processes, while paper can be cost-competitive or advantageous at mid-to-large volumes, especially factoring in branding value.
Kraft paper bags, enveloppes en carton ondulé, and rigid paper boxes are the most accessible starting points, since they’re widely manufactured, customizable at moderate minimum order quantities, and don’t require specialized barrier coatings for many non-perishable products.
For many applications, yes — particularly with corrugated structures and molded pulp cushioning designed for shipping protection. Cependant, for products needing strong moisture or grease barriers, paper typically requires additional coatings to match plastic’s performance.
Conclusion
Paperization is reshaping packaging decisions across categories — driven by consumer willingness to pay for sustainability, tightening regulation like the EU’s PPWR and single-use plastic restrictions, and a genuine market shift reflected in industry-scale data. But paper isn’t automatically the better choice in every case: composite materials, revêtements, and barrier needs all affect whether a paper format is actually more sustainable or compliant than the plastic it replaces. The brands getting this right are the ones evaluating material specs product-by-product, not applying a blanket “paper is greener” assumption.
If your brand is evaluating a shift from plastic to paper packaging, PackCCP’s team can help assess the right structure, matériel, and coating for your product category — get an instant quote to start the conversation.
For more on where paper packaging design is heading, voir 2026 paper bag design trends.